
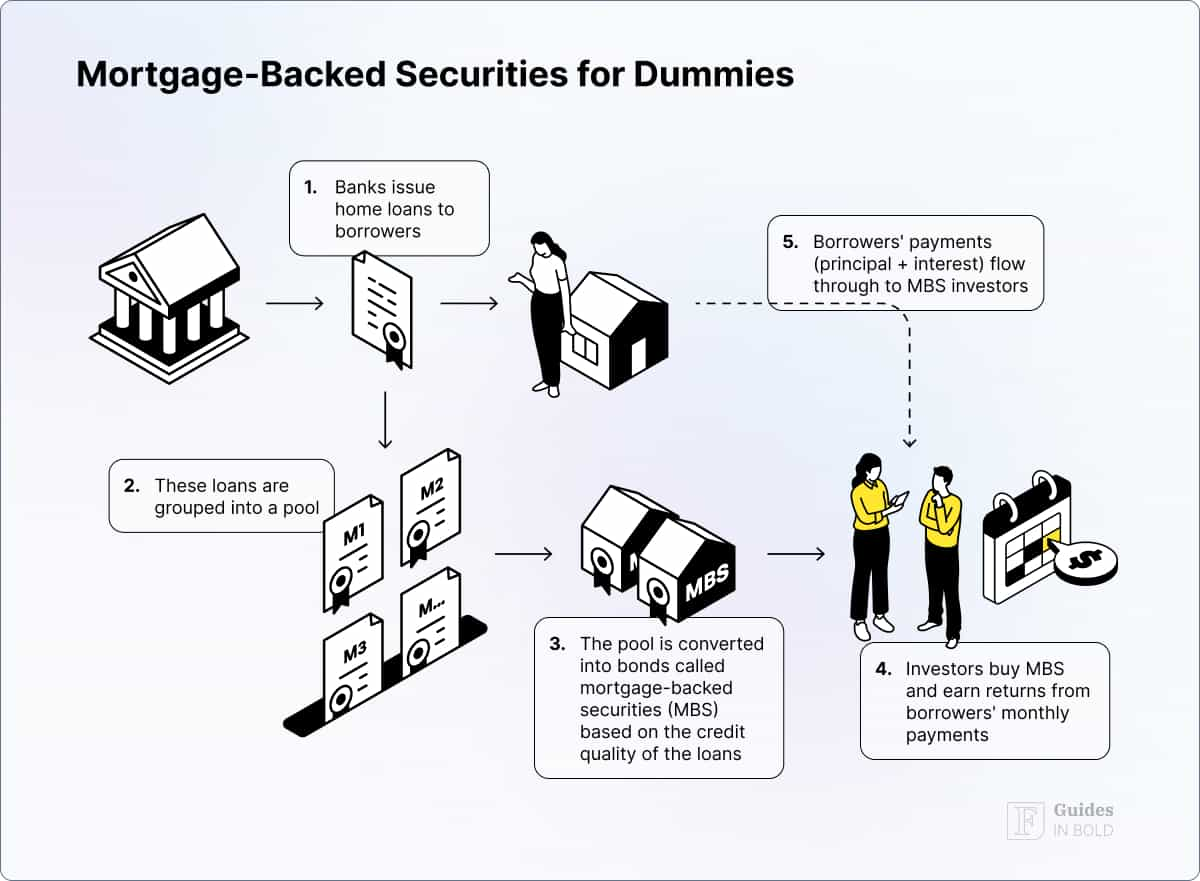
Imagine you're at a big party, and everyone is chipping in to buy a big house. In a way, that's what's happening with mortgage-backed securitization - multiple investors are pooling their resources to buy a portfolio of mortgages. This allows banks to free up capital, which they can then use to issue new mortgages to more people, creating a kind of financial ripple effect.
The process involves several key players, including originators (like banks), servicers (who collect payments), and rating agencies (who evaluate the risk of the securities). These players work together to create a financial ecosystem that supports the mortgage market, and allows people to buy homes they might not have been able to afford otherwise. But, have you ever stopped to think about the math behind it all?
It's actually pretty fascinating - the value of the securities is determined by the cash flows from the underlying mortgages, which are based on interest rates, loan terms, and other factors. This creates a complex web of financial relationships that can be tricky to navigate, but also offers opportunities for investors to diversify their portfolios and potentially earn higher returns. So, why is this concept so cool?
For one thing, mortgage-backed securitization has democratized access to credit, allowing more people to buy homes and achieve their dreams of homeownership. It's also created a global market for mortgage-backed securities, which can be traded and sold like other financial instruments. But, what about the risks involved - like the potential for defaults and market fluctuations?
 The Great Recession Explained (2007-2009) | Economic Downturn

