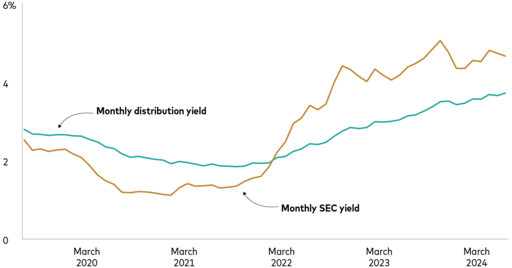
Think of SEC yield as that reliable friend who tells you the truth, even when it hurts. It’s a standardized measure that looks at a fund’s net income over the last 30 days, assuming you hold onto it like a stubborn barnacle for a year. Meanwhile, distribution yield is the loud cousin who shows up to family reunions wearing sequins and handing out free samples. It takes the actual payouts you’ve received over the past year and divides them by the current price. One is a sober prediction; the other is a blooper reel of what already happened.
Here’s the weirdest part: distribution yield can be three times bigger than SEC yield, and everyone still acts like that’s totally normal. It’s the financial equivalent of a guy claiming he’s 6’5” because he’s wearing platform shoes. The SEC yield strips away the platform shoes—and the hat.
The Great Dividend Illusion
Let me give you a real example that will make your eyebrows jump. Imagine a bond fund with a distribution yield of 8%. You think, “Sweet! I’m getting rich!” But check the SEC yield—it might be 4%. What gives? The fund likely returned some of your own principal to you as a “dividend,” like a bank robber handing you a wallet and saying, “Look what I found!” It’s called a return of capital, and it’s basically the fund saying, “Here’s your money back, but with a nice bow on it.”
In fact, a study by Morningstar found that nearly 40% of closed-end funds use return of capital to pump up their distribution yields. That’s like a chef serving you the same soup, but telling you it’s a new recipe because he added a single crouton. The SEC yield exposes this trickery because it only counts the actual income the fund generated, not the financial sleight-of-hand.
 Total Bond: 23 years of SEC yield and distribution yield - Bogleheads.org

